Timeline & Evolution
The History of Mintos: From 2015 Launch to MiFID II Licence
Chronological overview of Mintos from its founding in Riga to becoming the largest EU P2P marketplace, through originator issues in 2022 and subsequent MiFID II restructuring.
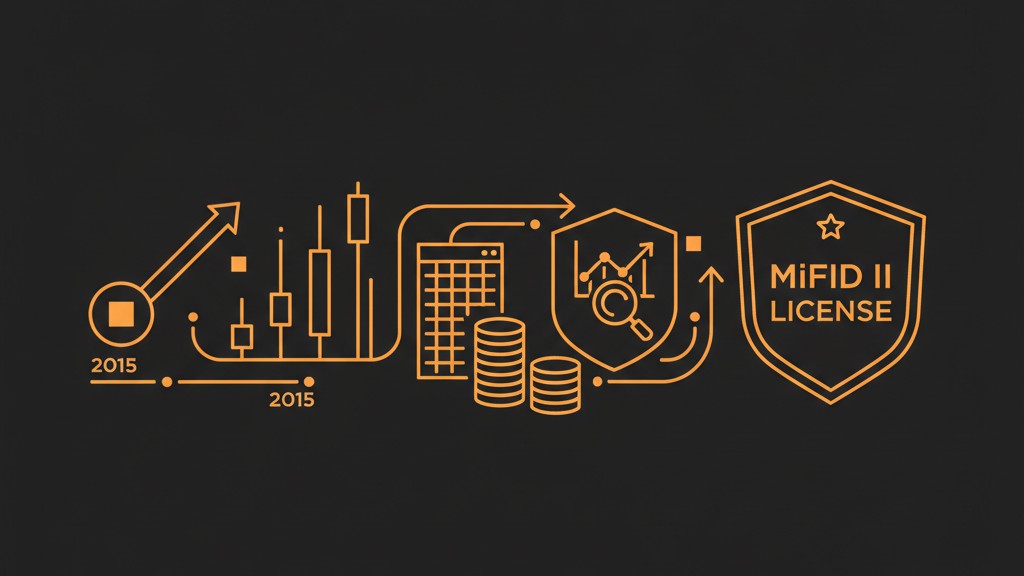
Key milestones: Founded 2015 in Riga, Latvia. Grew to over 700,000 investors and EUR 12.4 billion cumulative volume. Restructured into MiFID II-regulated Notes following originator issues in 2022. Now holds a MiFID II investment services licence from Latvijas Banka.
2015: Founding and Launch in Riga
Mintos was founded in 2015 in Riga, the capital of Latvia. The platform launched as a peer-to-peer lending marketplace, a model that connects retail investors directly with loans originated by third-party lending companies. The founding concept was to aggregate loan supply from multiple originators across Europe and make those loans available for purchase by individual investors. This marketplace structure distinguished Mintos from single-originator P2P platforms and from direct lending operations that issue their own loans. The founding team chose Riga as the headquarters city, placing the company within Latvia's emerging fintech sector.
From the outset, Mintos operated as a marketplace intermediary, not a lender. Originators - licensed lending companies in their home jurisdictions - would underwrite and issue consumer, business or real estate loans, then offer those loans for sale on the Mintos platform. Investors could review loan data and purchase claims against individual loans or use automated investment tools to build a diversified portfolio. The platform earned a fee from originators for providing investor access, while investors aimed for returns generated by loan interest payments. This structure meant that credit risk remained with the originators and their borrowers, not with Mintos itself.
Growth Phase: Building the Largest EU P2P Marketplace
Between 2015 and the early 2020s, Mintos expanded its originator network and investor base. The platform added originators from multiple EU member states and adjacent markets, offering loan types including consumer credit, business finance, car loans, invoice financing and real estate-backed debt. This geographic and product diversification attracted investors seeking exposure to different risk profiles within a single platform account. By the time the platform reached maturity, it reported over 700,000 registered investors and more than EUR 12.4 billion in cumulative volume since inception - figures that positioned Mintos as the largest P2P lending marketplace in the European Union measured by these metrics.
During this growth phase, Mintos introduced several operational features that became defining characteristics of the platform. The secondary market allowed investors to sell their loan claims to other investors before maturity, providing liquidity that was uncommon among P2P platforms at the time. Auto-invest tools automated portfolio construction based on investor-defined criteria such as target return, loan type, originator rating and geographic region. Public originator-level risk disclosure gave investors access to financial statements, historical default rates and other data points used to assess originator creditworthiness. These features contributed to the platform's reputation as a data-forward, investor-friendly marketplace.
2022: Originator Issues and Platform Response
In 2022, Mintos publicly reported issues affecting several originators on the platform. Some originators defaulted on their obligations, meaning they failed to remit payments to investors holding claims against loans they had sold. Other originators entered restructuring processes that delayed or reduced investor recoveries. These events exposed a structural risk inherent to the marketplace model: the platform intermediates between investors and originators but does not guarantee originator performance. Where an originator fails, investors holding that originator's loans face the risk of partial or total loss of capital, even if the underlying borrowers continue to make payments.
The 2022 originator issues prompted Mintos to restructure its product offering. The company moved away from the pure marketplace model - where investors purchased direct claims against individual loans - toward a regulated investment product called Notes. Under the Notes structure, investors buy debt securities issued by Mintos itself, and Mintos uses the proceeds to purchase loan claims from originators. This change brought the platform under MiFID II, the Markets in Financial Instruments Directive, which governs investment services in the European Union. Latvijas Banka, Latvia's central bank and financial regulator, granted Mintos a MiFID II investment services licence, formalising the company's status as a regulated investment firm.
The shift to Notes also brought Mintos under the scope of Latvia's investor compensation scheme, which covers up to EUR 20,000 per investor for eligible claims against the firm in the event of regulatory insolvency or similar failures. It is essential to note that this compensation scheme covers claims against Mintos as a firm - for example, if Mintos failed to return client funds held in segregated accounts - and does not cover borrower defaults or originator failures. The risk of partial or total loss of capital from originator or borrower performance remains with the investor, as it does in any P2P or debt investment structure.
Current Structure: MiFID II Regulation and Notes
As of 2026, Mintos operates under its MiFID II investment services licence from Latvijas Banka. The platform continues to aggregate loans from multiple originators, but the legal structure now places the direct originator relationship with Mintos rather than with individual investors. Investors purchase Notes from Mintos, and Mintos purchases loan claims from originators. Returns are still derived from the underlying loan cash flows, and the same originator risk exists, but the regulated Notes structure provides a formal framework for investor rights and firm obligations.
The platform targets returns in the range of 9-11% annually, depending on investor choices regarding originator mix, loan type and risk profile. Minimum investment remains EUR 50. The secondary market continues to operate, allowing investors to sell Notes to other investors before maturity. Auto-invest tools remain a core feature, automating portfolio construction and rebalancing. Public originator ratings and financial disclosures remain available, enabling investors to perform their own due diligence on the originators whose loans underpin the Notes they purchase.
Mintos' investor base now exceeds 700,000 registered accounts, and cumulative volume since 2015 stands above EUR 12.4 billion. These figures reflect the platform's scale within the European P2P and alternative lending sector. The MiFID II licence and investor compensation scheme - limited as it is to firm claims, not borrower defaults - represent regulatory milestones for a sector that historically operated outside traditional financial services regulation. The platform's history illustrates both the growth potential and the structural risks of the P2P marketplace model, particularly the dependency on third-party originator performance and the challenge of maintaining investor confidence when originators fail.
Current Mintos Facts (2026)
- Founded
- 2015, Riga, Latvia
- Regulator
- Latvijas Banka, MiFID II investment services licence
- Cumulative volume
- EUR 12.4 billion+ since 2015
- Investor base
- 700,000+ registered accounts
- Compensation scheme
- EUR 20,000 per investor, covers firm claims only (not borrower defaults)
- Minimum investment
- EUR 50
Lessons from Mintos' Evolution
The history of Mintos offers several lessons for investors evaluating P2P platforms. First, scale does not eliminate risk. Mintos grew to become the largest EU P2P marketplace by volume and investor count, yet originator failures in 2022 demonstrated that platform size does not guarantee originator performance or protect investors from capital loss. Second, regulatory status matters but has limits. The MiFID II licence and investor compensation scheme provide a formal legal framework and limited protection against firm failure, but they do not cover the primary risk in P2P lending: borrower and originator defaults. Investors must assess originator creditworthiness independently, using the data the platform provides.
Third, product structure affects risk distribution. The shift from direct loan claims to regulated Notes changed the legal relationship between investors and originators, but the economic risk remains the same. Investors are still exposed to originator performance through the Notes they purchase. Fourth, secondary markets provide liquidity but not principal protection. The ability to sell Notes before maturity reduces illiquidity risk, but sale prices reflect market conditions and investor demand. If an originator experiences difficulties, secondary market prices for Notes backed by that originator's loans typically fall, and investors seeking early exit may realise a loss.
Finally, transparency is a necessary but not sufficient condition for informed investment. Mintos publishes originator financial statements, historical default rates and other risk metrics, giving investors more data than many competing platforms. Yet data availability does not ensure that all investors will interpret the data correctly or act on warning signs before losses occur. Investors comfortable with the P2P asset class and willing to perform ongoing due diligence on originators may find Mintos' transparency useful; those seeking a passive, low-risk savings vehicle will find this history a reminder that P2P lending carries a risk of partial or total loss of capital.
What Happens Next
Mintos' trajectory from 2015 to 2026 reflects broader trends in European alternative finance: rapid growth in the late 2010s, stress-testing of business models during the 2020s and a regulatory push toward formalised oversight. The MiFID II licence places Mintos within the same regulatory perimeter as traditional investment firms, but the underlying economics of P2P lending - credit risk, originator dependency, limited recourse in default scenarios - remain unchanged. Investors evaluating Mintos today assess a platform with an eleven-year track record, regulatory standing and substantial scale, alongside a documented history of originator issues and the structural risks inherent to the marketplace model.
The platform's future will depend on its ability to manage originator risk, maintain investor confidence and adapt to evolving EU regulations governing alternative finance. The 2022 originator issues and subsequent restructuring represent the most significant inflection point in Mintos' history to date. Whether the Notes structure and MiFID II framework prove sufficient to contain future originator failures, or whether additional stress events expose further weaknesses, remains to be seen. For now, Mintos stands as the largest P2P marketplace in the EU by reported metrics, with a history that illustrates both the sector's growth and its ongoing challenges.
Frequently Asked Questions
Mintos was founded in 2015 in Riga, Latvia. The platform launched as a P2P lending marketplace connecting retail investors with loans originated by third-party lending companies across Europe.
In 2022, Mintos publicly reported issues with several originators on the platform, including defaults and restructurings. The company responded by restructuring its product offering into MiFID II-regulated Notes, moving from a pure marketplace model to a regulated investment structure.
As of 2026, Mintos reports over 700,000 registered investors and more than EUR 12.4 billion in cumulative volume since 2015, making it the largest P2P lending marketplace in the European Union by these metrics.
Yes. Mintos operates under a MiFID II investment services licence issued by Latvijas Banka, the central bank of Latvia and the country's financial regulator. This licence permits the platform to offer regulated investment products.
Next step: Review the full risk warning to understand how Mintos' history and structure affect the risks you take when investing on the platform, or read Is Mintos Safe? for an in-depth assessment of current trustworthiness signals.